By: Victor J. Rosario
Introduction: Qualification Is the Real Barrier to Ownership
In Miami-Dade County, most residents are not blocked from economic advancement because they lack work ethic, ambition, or intelligence. They are blocked because they fail to meet underwriting thresholds. Banks do not evaluate hope. They evaluate ratios. Mortgage lenders assess debt-to-income. Auto lenders calculate payment-to-income ceilings. SBA programs test global cash flow, liquidity reserves, and debt service coverage durability. This is not a moral system. It is a mathematical one. The real barrier in Miami-Dade is qualification power, and qualification power is simply the measurable financial strength that determines whether a resident is approved or declined.
Qualification power is the sum of documented recurring income, income consistency, liquidity reserves, debt obligations, credit utilization, and repayment history. When these metrics miss by small margins, the application is declined. When they improve even modestly, approvals rise dramatically. Project Fund is structured to improve qualification power across the county without requiring banks to lower standards or rewrite rules. Instead, it strengthens residents so they meet existing standards. When thousands of residents simultaneously improve their underwriting metrics, lending capital flows more confidently into the local economy, and that capital flow becomes the engine of structural transformation.
The Hidden Constraint: Underwriting Algorithms, Not Opportunity
Modern lending decisions are increasingly automated. Mortgage files are run through Desktop Underwriter (DU) and Loan Product Advisor (LPA) systems that evaluate risk layers simultaneously. Auto lending is priced through risk-tier matrices driven by FICO bands and payment-to-income stress thresholds. SBA programs incorporate global cash flow projections and repayment durability models. In each category, approval is a probability output, not a personal evaluation, and the result is often decided before a human being ever forms an opinion about the borrower.
A borrower may be declined not because they are incapable of repayment, but because the algorithm projects insufficient margin between income and obligation. A 2% difference in total debt-to-income. A reserve shortfall of two months. A marginal credit utilization spike. These small variances alter automated risk grading. Project Fund changes those margins. When recurring documented income increases at scale and liquidity buffers strengthen across thousands of households, the distribution curve of risk shifts. The underwriting software does not need to be convinced. It responds to data inputs. This is the core principle: change the inputs, approvals change automatically.
Understanding How Mortgage Underwriting Actually Works
Mortgage approval in Miami-Dade is primarily governed by two ratios: front-end debt-to-income, which measures housing expenses relative to gross income, and back-end debt-to-income, which measures total monthly debt obligations relative to gross income. Conventional lending commonly caps total DTI in the 36% to 43% range depending on credit strength, reserves, and compensating factors. The standard is not flexible sentiment. It is a threshold system. Residents either fit inside the allowable bands or they do not.
A household earning $80,000 annually generates roughly $6,667 per month in gross income. At a 43% total DTI cap, total allowable monthly debt service equals about $2,867. That figure must include mortgage payment, property taxes, homeowner’s insurance, and HOA fees. In a Miami-Dade environment where insurance premiums and taxes are elevated, this income band often qualifies for a home in the $300,000 to $375,000 range depending on interest rates and debt load. Now consider what happens if documented recurring income increases to $100,000 annually. Gross monthly income becomes $8,333. At the same 43% threshold, allowable monthly debt rises to about $3,583. That difference of $716 per month in allowable debt service can translate into $75,000 to $125,000 in additional purchasing power depending on the rate environment. The underwriting formula did not change. The resident’s qualification metrics improved.
When 10,000 renter households increase qualification capacity by $100,000 each, that represents $1 billion in additional housing transaction capacity. That $1 billion does not sit idle. It activates appraisal services, title companies, home inspections, insurance carriers, local contractors, furniture retailers, and additional property tax revenues. Each approved mortgage multiplies economic activity. Homeownership also stabilizes neighborhoods in ways that renter volatility cannot. Owners maintain properties differently, community engagement rises, school continuity improves, crime volatility declines, and appreciation becomes more predictable. Qualification expansion becomes neighborhood stabilization policy, not just personal wealth improvement.
Liquidity Reserves: The Hidden Approval Lever
Income is only one part of the underwriting equation. Liquidity reserves play a decisive role in approval decisions because reserves represent shock absorption capacity. Many lenders require two to six months of mortgage payments in reserve after closing. SBA programs often require 10% to 20% equity injection and look carefully at personal liquidity to evaluate whether the borrower can survive unexpected revenue disruption. In practice, the same borrower can be approved or declined depending on whether documented reserves signal durability.
A borrower earning $90,000 with only $3,000 in reserves may face heightened underwriting scrutiny, conditions, or a flat decline. The same borrower with $15,000 in documented reserves presents reduced default risk. Underwriters interpret liquidity as the ability to absorb job loss, medical events, or temporary income dips. Stronger liquidity reduces perceived risk. Reduced perceived risk increases approval rates. When liquidity improves countywide, foreclosure probability declines. Lower default rates recalibrate lender confidence in the region. Over time, this can influence pricing models, competitive lending dynamics, and the willingness of institutions to deploy volume.
Auto Financing as Workforce Infrastructure
Vehicle financing is often treated as consumer spending, but in Miami-Dade it functions as workforce infrastructure because public transportation does not connect every employment corridor efficiently. Many residents rely on vehicles for income generation, commute reliability, and access to higher-paying jobs. Auto lenders assess payment-to-income ratios, credit risk tiers, and stability signals that translate directly into interest rate pricing and maximum loan amounts. When documented income increases, payment-to-income strain declines and borrowers often move into stronger tiers that produce better terms and more reliable approvals.
If a household previously qualified for $25,000 and now qualifies for $35,000, that additional margin often enables the purchase of a newer, safer vehicle with lower maintenance volatility. Reduced repair disruptions mean fewer missed workdays. Stable employment reinforces credit reliability. Stronger credit improves mortgage and SBA eligibility. If 30,000 households improve vehicle financing capacity by an average of $7,500, that represents $225 million in automotive transactions, supporting dealership expansion, mechanic employment, parts suppliers, and sales tax revenue. Reliable transportation strengthens workforce continuity. Workforce continuity strengthens credit performance. Credit performance strengthens qualification power across financial categories.
SBA Lending: Enterprise Formation at Scale
SBA financing creates exponential impact because it generates new enterprise formation rather than passive asset ownership. SBA 7(a) underwriting evaluates debt service coverage ratio, global cash flow analysis, equity injection, personal liquidity, and industry risk profile. A borrower whose household income increases and whose liquidity strengthens presents stronger DSCR projections and improved durability. That profile makes it easier to secure $250,000 to $500,000 in startup or expansion capital, turning qualified residents into operating businesses.
Assume 3,000 Miami-Dade residents secure SBA financing averaging $300,000. That equals $900 million in entrepreneurial capital deployment. These funds finance commercial leases, equipment purchases, inventory, payroll expansion, and professional services. If each business employs five individuals on average, that creates 15,000 direct jobs. Indirect and induced employment can push the total above 25,000. Entrepreneurial density transforms corridors: vacant storefronts fill, local supply chains expand, property owners invest in improvements, commercial values rise, and sales tax revenue increases. Over ten years, if SBA deployment averages $300 million annually due to strengthened qualification profiles, cumulative entrepreneurial capital formation exceeds $3 billion, and with multiplier effects, total circulation impact can approach $6 billion.
Secondary Market Effects: Fannie, Freddie, and Capital Confidence
Mortgage loans in Miami-Dade are not held solely by local banks. Most are sold into the secondary market and priced through risk modeling that incorporates delinquency volatility, repayment consistency, and geographic concentration exposure. If a region demonstrates stable repayment patterns and low delinquency volatility over sustained periods, it improves its reputation inside secondary market analytics, and lenders often compete more aggressively in regions with stronger portfolio performance because stable portfolios invite volume appetite.
If Project Fund strengthens debt service durability and reduces delinquency rates across Miami-Dade over a decade, the county’s aggregate credit profile improves. Lenders respond to stable portfolios by increasing appetite for origination volume. Increased appetite creates competition. Competition narrows spreads. Even a modest 0.25% improvement in mortgage pricing across billions in loan volume represents millions in retained resident capital over time, and that retained capital compounds locally through spending, savings, and reinvestment.
The Multiplier of Down Payment Formation
Down payments are one of the most significant barriers to homeownership. In Miami-Dade’s price environment, a 10% down payment on a $450,000 home equals $45,000. Many households cannot accumulate that amount without years of constrained saving. When qualification power improves through increased recurring income and structured liquidity reinforcement, down payment accumulation timelines compress. Households move from five-year horizons to two- or three-year horizons, and that time compression increases economic velocity.
If 15,000 households accelerate down payment formation by three years each, that means $675 million in capital enters the housing market earlier than it otherwise would. Velocity matters because when capital moves faster, transaction density rises; when transaction density rises, employment expands; when employment expands, documented income improves; and when documented income improves, qualification power strengthens further. The cycle becomes self-reinforcing.
Commercial Real Estate Stabilization Through SBA Density
Small businesses anchor commercial corridors. When SBA approvals increase, storefront occupancy stabilizes. Occupancy stability improves landlord cash flow. Stable landlord cash flow improves commercial valuations. Improved valuations strengthen municipal tax bases without raising tax rates. If vacancy rates decline by even 5% across key Miami-Dade corridors due to increased enterprise formation, commercial property values can rise measurably. A $200 million increase in commercial valuation translates directly into higher property tax revenue without any change in rate.
This dual expansion of residential ownership and commercial enterprise density produces durable fiscal resilience because it stabilizes both sides of the tax base simultaneously. When residents own and businesses operate, counties become less fragile and less dependent on external intervention.
Credit Score Distribution Shift
Credit scores are statistical reflections of repayment patterns, utilization ratios, and credit mix. When household liquidity increases and income margins widen, residents are less likely to miss payments or rely heavily on revolving credit to survive short-term shocks. Over time, these improvements shift credit score distributions upward, not through artificial manipulation but through durable repayment behavior supported by stronger balance sheets.
If average credit scores across Miami-Dade increase by even 25 to 40 points over a decade due to strengthened liquidity and repayment consistency, borrowing costs across mortgages, auto loans, and small business lines compress meaningfully. Interest rate tiers narrow. Lower rates reduce payment strain. Reduced strain lowers delinquency probability further. A county-wide credit score distribution shift changes the cost-of-capital environment silently but powerfully, creating an upward spiral of lower friction and higher approval density.
Insurance Stability and Risk Layer Reduction
Miami-Dade’s housing affordability strain is not only mortgage-driven. Insurance premiums materially affect qualifying ratios and monthly payment thresholds. When liquidity improves and homeowners demonstrate stronger financial profiles, claim volatility can decline because stronger financial profiles correlate with better maintenance behavior and reduced deferred repairs. While insurance markets are complex and heavily influenced by reinsurance pricing and catastrophe exposure, localized stability reduces risk layers inside underwriting models.
Over time, reduced claim frequency in stabilized neighborhoods can influence carrier behavior at the margin. Lower insurance volatility improves housing qualification sustainability because residents are less likely to be disqualified by payment shock from premium spikes or forced coverage changes.
Workforce Mobility and Income Scaling
Reliable transportation expands access to higher-paying employment corridors. When residents can qualify for dependable vehicles, they are no longer constrained to jobs within limited geographic radii. Expanded mobility increases labor competition because employers must compete for workers who can now reach broader job markets. Wage growth accelerates when workforce mobility expands, and wage growth further strengthens mortgage and SBA qualification.
This is a structural labor-market enhancement, not merely an auto-financing improvement. Mobility expands income access, income expands qualification, qualification expands ownership and enterprise, and ownership and enterprise stabilize neighborhoods.
Municipal Bond Rating Implications
Counties are evaluated by rating agencies based on economic diversity, tax base strength, employment stability, and revenue predictability. If Project Fund strengthens ownership rates, enterprise density, and repayment stability over sustained periods, Miami-Dade’s fiscal profile strengthens. Even incremental improvement in fiscal metrics can reduce borrowing costs for infrastructure projects, and reduced borrowing costs allow more infrastructure deployment without raising taxes.
Infrastructure investment supports property values. Property values reinforce tax base stability. Stability improves bond confidence further. Household-level capital access ripples upward into municipal finance, and municipal finance feeds back into household stability through improved infrastructure and service reliability.
Ten-Year Structural Impact on Miami-Dade
A conservative ten-year scenario illustrates scale without requiring miracles. If 20,000 renter households transition into ownership at an average home value of $450,000, housing transaction volume equals $9 billion. At a 1.8% effective property tax rate, annual property tax revenue increases by approximately $162 million, and over ten years cumulative property tax generation exceeds $1.6 billion before accounting for appreciation.
Simultaneously, if 5,000 residents secure SBA loans averaging $250,000, $1.25 billion in entrepreneurial capital enters circulation, and if those businesses average five employees each, 25,000 direct jobs are created. Auto financing expansion adds $225 million in vehicle transactions. Combined, these categories represent multi-billion-dollar reinforcement within one decade without raising taxes and without external intervention.
Twenty-Year Compounding Equity Formation
Compounding ownership is how counties become resilient. At 4% annual appreciation, a $450,000 home grows to approximately $985,000 over twenty years. If 20,000 households hold property long term, cumulative equity formation approaches $10.7 billion. That equity becomes leverage for education financing, second business launches, intergenerational wealth transfer, and retirement security.
SBA deployment over twenty years at $300 million annually totals $6 billion in direct capital, and with multiplier effects, total circulation can reach $12 billion to $15 billion. This is how counties transform: not through one-time programs, but through compounding ownership and enterprise formation.
Thirty-Year Generational Transformation
Over thirty years, the transformation becomes generational. A $450,000 home appreciating at 4% annually reaches approximately $1.46 million. If 25,000 additional households secure ownership and retain property long term, cumulative equity formation can exceed $25 billion. Entrepreneurial capital formation over three decades can surpass $9 billion directly and approximately $18 billion with multiplier effects.
Neighborhood stability increases. Displacement risk decreases. Intergenerational resilience strengthens. This is not speculation. It is compound growth mathematics applied to qualification power.
Systemic Risk Reduction Across the County
When liquidity improves across households, systemic risk declines. Default probability decreases. Foreclosure volatility reduces. Credit score averages increase. Lender competition strengthens. As repayment performance improves, financial institutions recalibrate regional risk assessments, and over time borrowing costs can compress marginally, expanding access further.
Municipal strain decreases as well. Fewer foreclosures mean fewer abandoned properties. Reduced eviction rates lower emergency social service demand. Stable neighborhoods reduce public safety expenditure volatility. Qualification expansion is not merely financial. It is infrastructural.
Resilience During Economic Downturns
Recessions test balance sheets. Counties with thin liquidity margins experience foreclosure spikes, eviction waves, and municipal strain. Counties with stronger liquidity buffers absorb downturn shocks more effectively. If Project Fund increases median household reserves by even three months of expenses, Miami-Dade’s vulnerability during contraction declines significantly. Reduced foreclosure waves prevent value collapses. Stable values protect tax revenue. Stable revenue preserves public services. Resilience reduces long-term damage from cyclical downturns, keeping neighborhoods from being permanently scarred by short-term macroeconomic stress.
Intergenerational Wealth Transfer Modeling
When 25,000 households accumulate $1 million or more in home equity over thirty years, aggregate generational asset transfer approaches $25 billion. If even 30% of that equity is leveraged by the next generation for education or entrepreneurship, long-term productivity expands. Educational attainment correlates strongly with income growth and reduced delinquency. Entrepreneurial inheritance strengthens enterprise density. This compounding effect reduces long-term reliance on assistance systems. Wealth transfer is not merely personal. It is macroeconomic.
The Psychological Multiplier Effect
When residents believe qualification is achievable, behavior shifts. Savings discipline increases because the goal feels real. Credit management improves because the payoff becomes tangible. Long-term planning becomes rational rather than speculative. Risk-taking becomes calculated rather than desperate. Communities transition from reactive survival mode into proactive investment mode, and that psychological shift amplifies the outcomes beyond what spreadsheets capture.
Confidence anchored in measurable improvement becomes a stabilizing civic force. It changes what people believe is normal, and what becomes normal becomes scalable.
Behavioral Finance and Expectation Recalibration
When residents consistently see neighbors qualifying for mortgages, auto financing, and SBA capital, expectation baselines reset. Qualification becomes normalized rather than exceptional. Savings behavior becomes socially reinforced. Credit discipline becomes culturally embedded. Economic ecosystems are partially psychological, and confidence grounded in measurable improvement increases risk-adjusted participation in investment and enterprise. A culture of qualification replaces a culture of rejection, and that cultural shift sustains the financial shift.
Capital Retention Within the County
Every stable mortgage that results in long-term homeownership increases the probability that spending remains local. Homeowners invest in local contractors, local services, and local businesses. SBA-funded enterprises hire locally and source locally where possible. Vehicle purchases support dealership and mechanic ecosystems. Capital that circulates locally multiplies locally. When residents qualify, capital does not exit the county prematurely. It compounds internally, and over decades that retained circulation difference can measure in tens of billions.
Structural Transformation Defined
Incremental growth is linear. Structural transformation is exponential. If over thirty years Miami-Dade generates $25 billion in residential equity formation, $9 billion in direct SBA deployment, approximately $18 billion in enterprise multiplier circulation, billions in tax base stabilization, and measurable infrastructure borrowing savings, the cumulative structural impact exceeds $50 billion. This scale of transformation is not achieved through slogans. It is achieved through underwriting mathematics applied at scale.
Final Synthesis: Qualification as the Engine of Sovereignty
Qualification power determines whether residents remain renters, marginal borrowers, or full participants in capital markets. When qualification expands across mortgages, auto financing, and SBA lending simultaneously, Miami-Dade experiences synchronized capital access acceleration. Project Fund strengthens the inputs underwriting systems measure: recurring documented income, liquidity durability, repayment reliability, and documented consistency. It respects standards. It does not demand exceptions. It produces strength.
When thousands qualify, billions flow. When billions flow locally, equity compounds. When equity compounds, sovereignty strengthens. This is not speculative theory. It is financial mechanics, and financial mechanics, aligned at scale, reshape entire regions.
Appendix: Financial Modeling Assumptions, Risk Controls, and Projection Framework
All projections in this document are built on conservative, industry-standard underwriting parameters derived from conventional lending frameworks currently applied in Miami-Dade County. Mortgage modeling assumes total debt-to-income ratios capped at 43% in alignment with common conforming guidelines. Interest rate projections are modeled within a 6% to 7% long-term band to reflect cycle realism without assuming speculative compression. Property tax modeling assumes an effective rate near 1.8%, inclusive of municipal overlays and non-ad valorem assessments. Insurance modeling reflects elevated South Florida risk pricing without assuming catastrophic volatility spikes. SBA lending projections assume minimum 1.25x DSCR and equity injection between 10% and 20%, consistent with standard 7(a) and 504 structures. Auto financing projections assume payment-to-income thresholds consistent with prime and near-prime tiers without relying on subprime expansion. No projection relies on relaxed standards. All modeling assumes existing underwriting frameworks remain intact.
Household qualification shift modeling assumes incremental documented recurring income increases ranging from $15,000 to $25,000 annually for qualifying households. This is not modeled as a speculative windfall, but as structured, recurring, documentable income capable of being recognized by underwriting systems. Under a $20,000 annual increase scenario, gross monthly income rises by approximately $1,667, and at a 43% DTI threshold, qualifying debt capacity expands by roughly $717 per month. At current amortization structures, this equates to approximately $90,000 to $125,000 in additional home purchasing power depending on rates. If 10,000 households experience this shift, incremental housing transaction capacity ranges between $900 million and $1.25 billion. The sensitivity model assumes only a 40% conversion rate from improved qualification to actual purchase within five years, and even under that conservative assumption, housing activation exceeds $400 million.
Liquidity stress buffer calculations assume average reserve reinforcement of $10,000 per participating household. For 50,000 households, that equals $500 million in additional documented liquidity. Stress simulations assume a six-month regional employment contraction scenario. Under baseline liquidity constraints, foreclosure spike probability rises significantly within 90 to 180 days. Under reinforced liquidity conditions, foreclosure incidence drops materially because households possess greater payment endurance. Default elasticity modeling shows that even a 2% reduction in delinquency rates across large mortgage portfolios improves portfolio performance and regional risk perception. Liquidity is treated as systemic shock insulation rather than optional savings.
SBA deployment multiplier framework assumes average loan sizes of $250,000 to $300,000 and job creation ratios modeled conservatively at five direct employees per funded enterprise. Economic multiplier modeling uses a restrained 1.8x to 2.0x circulation factor, meaning each dollar deployed generates between $1.80 and $2.00 in broader activity through payroll, vendor contracts, and reinvestment. Under a $300 million annual SBA deployment sustained ten years, direct capital equals $3 billion, and multiplier circulation reaches approximately $5.4 to $6 billion. This modeling excludes appreciation effects in commercial valuations, which represent upside.
Long-term equity compounding assumes 4% annual appreciation, intentionally conservative relative to aggressive cycles while acknowledging volatility. Using standard compounding, a $450,000 property reaches approximately $1.46 million over thirty years. If 25,000 households retain ownership over that period, aggregate equity formation approaches $25 billion. These projections do not assume speculative bubbles. They assume disciplined, moderate long-term growth consistent with inflation-adjusted housing behavior.
Municipal fiscal reinforcement modeling uses an effective property tax rate near 1.8%. Under $9 billion in residential transaction expansion over ten years, incremental annual property tax generation equals approximately $162 million, and cumulative revenue exceeds $1.6 billion before appreciation. Bond rating sensitivity modeling recognizes that diversified enterprise density, improved employment stability, and tax base strengthening can influence municipal credit evaluation. Even a 0.25% reduction in municipal borrowing costs on multi-billion-dollar issuance produces meaningful long-term savings. This appendix does not assume upgrades. It models potential improvement under sustained performance.
Risk factors were stress-tested including interest rate volatility beyond 8% for extended periods, insurance instability tied to reinsurance spikes, hurricane clustering, national recession exceeding 18 months, and federal regulatory shifts. Under these stress conditions, qualification expansion remains beneficial because strengthened liquidity and income margins increase survival probability relative to baseline household fragility. The model does not depend on perfect cycles. It depends on stronger household balance sheets.
An inflation-adjusted scenario was reviewed under 2.5% long-term inflation assumptions to avoid nominal illusion bias. Ownership remains protective in inflationary environments because fixed-rate debt amortizes in nominal dollars while asset values adjust. Qualification power becomes more valuable during inflation because access to fixed-rate ownership and durable liquidity buffers reduces exposure to rising costs. Behavioral and cultural reinforcement variables were also recognized because increased approval visibility normalizes savings and credit discipline, and repayment consistency strengthens systemic performance. All projections remain within conservative boundaries: participation rates reduced below theoretical maximums, appreciation restrained, multipliers mid-range, and no speculative subsidies assumed. The transformation described relies on structured improvement of underwriting inputs across thousands of households, because underwriting systems respond to measurable strength, and strength at scale reshapes regions.
FAQ — Qualification Power, Underwriting, and the Project Fund Model
1) What does “qualification power” mean in plain language? Qualification power is your measurable financial strength in the eyes of underwriting systems. It is the combination of documented recurring income, income consistency, liquidity reserves, total debt obligations, credit utilization, and repayment history that determines whether you are approved or declined. It is not about whether you are a good person or hardworking. It is about whether the numbers land inside the approval bands that lenders and automated underwriting software use.
2) Why are so many Miami-Dade residents declined even when they can afford the payment? Because underwriting decisions are not based on “I think I can handle it.” They are based on margin math. Automated systems test whether you have enough buffer between income and obligation to survive stress events without default. A small shortfall can trigger a decline: a debt-to-income ratio slightly above threshold, reserves that are two months short, or credit utilization that spiked during a hard month. The system is designed to prioritize probability, not personal story.
3) What is Desktop Underwriter (DU) and Loan Product Advisor (LPA), and why do they matter? DU and LPA are automated underwriting engines used widely in mortgage lending to evaluate risk layers at once. They process a borrower’s file and generate an approval outcome based on multiple variables: income, debts, assets, reserves, credit profile, and other factors. In practice, these systems often determine the outcome before a human underwriter reviews anything in depth.
4) Is this about asking banks to lower standards or “change the rules”? No. The model does not depend on banks lowering standards. The model depends on residents strengthening the exact inputs underwriting systems already measure. When income and liquidity improve and repayment reliability increases, approvals rise automatically because the file grades better under existing standards.
5) How does recurring documented income change mortgage approval odds? Mortgage qualification is fundamentally tied to debt-to-income ratios. When documented income increases, allowable debt service increases at the same percentage cap, which expands the size of the mortgage a household can qualify for. The formula does not change. The capacity changes. This is why even moderate income reinforcement can unlock meaningful home purchasing power.
6) What role do liquidity reserves play in approvals? Liquidity reserves signal shock absorption. Lenders want to see that you can handle income disruption, unexpected expenses, or temporary job loss without missing payments. Strong reserves can reduce perceived risk even when income is similar, and that reduction in perceived risk improves approval probability.
7) Why do reserves matter so much in Miami-Dade specifically? Because Miami-Dade cost layers are heavier than many regions. Insurance, property taxes, HOA fees, transportation costs, and everyday living expenses compress margins. Underwriting systems react to that compression. Strong reserves are one of the most direct ways to prove durability in a high-cost environment.
8) How does this model affect renters trying to become homeowners? Renters are often blocked by down payment timelines, reserve requirements, and DTI margins that are too thin under current incomes. By strengthening documented income and reserves, the model compresses down payment timelines, improves approval odds, and expands purchasing power without changing lending standards.
9) What does “down payment acceleration” mean? It means households reach their down payment goal faster because their documented recurring income and liquidity position improves. Instead of needing five years to save, the timeline can compress to two or three years. When thousands of households accelerate simultaneously, capital enters the housing market earlier and economic velocity increases.
10) Why include auto financing in a plan about economic transformation? Because in Miami-Dade, vehicle access is workforce access. Many residents rely on cars to reach jobs, maintain stable hours, and access higher-paying corridors. When households qualify for more reliable vehicles on better terms, missed workdays decline, income stability improves, and credit performance strengthens—feeding back into mortgage and SBA qualification.
11) How does improved vehicle reliability strengthen credit? Reliable transportation reduces disruption. Fewer missed shifts means fewer late payments, fewer emergency credit card spikes, and more consistent cash flow. That consistency improves repayment patterns, reduces utilization volatility, and raises credit score trajectories over time.
12) What is the SBA pathway and why is it so important? SBA lending is one of the strongest tools for enterprise formation because it finances new businesses and expansions. SBA underwriting looks at debt service coverage, global cash flow, equity injection, liquidity, and risk profile. When household income and liquidity improve, SBA files become stronger and approvals become more achievable at scale.
13) Does this plan assume residents will take on risky debt? No. The strategy is not “borrow more.” The strategy is “qualify stronger.” Stronger qualification means better terms, better pricing, lower stress, and higher durability. Borrowing is not the goal. Ownership and enterprise formation are the goals, and both require balance-sheet strength.
14) What are “secondary market effects” and why should residents care? Most mortgages are sold into the secondary market, where portfolios are analyzed for delinquency volatility and risk. If Miami-Dade demonstrates stronger repayment performance over time, lenders become more confident deploying volume here. Greater volume appetite increases competition, and competition can narrow spreads, which keeps more money in residents’ pockets.
15) Can this model lower interest rates? It can influence pricing at the margins through improved risk performance and lender competition, especially over multi-year periods. Even small reductions—like a quarter point—matter when applied across billions in loan volume. The biggest immediate benefit, however, is improved approval probability and better tier placement.
16) How does credit score improvement happen at a county scale? When liquidity buffers grow and income margins widen, residents are less likely to miss payments or rely heavily on revolving credit. Over time, repayment consistency increases and utilization volatility decreases. If enough households experience this shift, the county’s credit score distribution moves upward, reducing the cost of capital across multiple categories.
17) How does this reduce foreclosures and evictions? Foreclosures and evictions often spike when households have thin reserves and cannot absorb shocks. Increasing liquidity durability and income margins reduces the probability of missed payments during stress events. Fewer distress events means fewer foreclosures, fewer abandoned properties, and more stable neighborhoods.
18) What does this mean for neighborhood stability? Ownership stabilizes residency, maintenance behavior, and community investment. More stable neighborhoods typically experience better school continuity, lower volatility in crime patterns, more predictable property values, and stronger local business ecosystems. Qualification expansion becomes a stabilization policy, not just a finance policy.
19) How does this help small business corridors? When SBA approvals rise, storefront occupancy increases. Occupancy stabilizes landlord cash flow, improves commercial valuations, and strengthens the tax base. Even modest declines in vacancy rates can create measurable corridor revitalization without tax hikes.
20) What about insurance costs—does this model address them? Insurance markets are complex, but household stability can reduce localized risk layers. Better maintenance behavior, fewer distress sales, and more stable neighborhoods can reduce claim volatility at the margin. Even when premiums remain high, stronger qualification and reserves make insurance cost layers more survivable inside monthly budgets.
21) Does this strategy require raising taxes? No. The model is designed to strengthen residents so they qualify more easily under existing systems, which increases transaction activity, ownership rates, enterprise density, and long-term tax base stability. That stability can improve municipal finances without increasing rates.
22) How does this connect to municipal bond costs and infrastructure? Counties are evaluated based on tax base strength, economic diversity, employment stability, and revenue predictability. If those metrics improve over time, borrowing costs for infrastructure can decline. Lower borrowing costs mean more infrastructure can be built with less pressure on families.
23) What happens during recessions—does this still work? Recessions test reserves. Counties with thin household buffers experience higher distress. If households have stronger liquidity and income margins, downturn shocks are absorbed more effectively, reducing foreclosure waves and protecting property values and tax revenue. Resilience reduces long-term damage from cyclical downturns.
24) Is this model realistic or is it “theory”? The mechanics are standard underwriting mechanics. Underwriting systems respond to measurable inputs. When income, reserves, and repayment reliability increase, approval probabilities increase. The “new” part is scale—engineering those improvements across thousands of households so the regional risk curve shifts.
25) What does success look like in one sentence? Success looks like tens of thousands of Miami-Dade households moving from rejection to approval—building ownership, reliable mobility, and enterprise formation—so capital stays local, equity compounds, and neighborhoods stabilize for generations.
Conclusion
Miami-Dade doesn’t have a “motivation problem.” We have a qualification problem — and that is exactly why so many hardworking residents feel stuck even while they’re doing everything right. The economy is not blocking people with effort; underwriting is blocking people with math. Automated lending systems don’t ask whether you’re a good parent, a loyal employee, a disciplined saver, or a resident who has held this county together through every storm. They measure recurring documented income, liquidity reserves, debt-to-income margins, credit utilization, repayment consistency, and buffer durability — then they output a probability score. That score decides whether you buy a home, refinance, replace a failing vehicle, or secure SBA capital to open the business you’ve been dreaming about. And in a high-cost county like ours — where insurance, rent, transportation, and basic living expenses compress household margins — even small gaps become hard walls. A 2% DTI miss. Two months short on reserves. A utilization spike because a family needed groceries, repairs, or medical care. Underwriting doesn’t see the story. It sees the numbers. So if we want structural transformation, we stop wasting time begging institutions to “be nicer,” and we do what real builders do: we change the inputs.
That is the foundation of a Residents-First Administration. We do not build policy around slogans. We build around measurable leverage points that scale. Project Fund is designed to strengthen the exact variables underwriting systems respond to — not through temporary relief, not through short-term patches, but through a durable expansion of qualification power across the county. When recurring documented income improves and liquidity buffers grow, approvals increase without any institution lowering standards. Mortgage access expands, homeownership rises, neighborhoods stabilize, and equity begins compounding instead of rent evaporating. Auto financing terms improve, transportation reliability rises, job access expands, wages climb, and workforce continuity strengthens credit performance. SBA approvals accelerate, storefronts fill, commercial corridors stabilize, payrolls expand, and entrepreneurship becomes a normal pathway instead of a rare exception. When those three channels expand together — ownership, mobility, and enterprise — Miami-Dade stops operating like a county that leaks capital and starts operating like a county that compacts capital, retains it, multiplies it, and reinvests it locally for decades.
This is why I describe qualification power as economic sovereignty. Because sovereignty is not a speech — it is the ability of residents to participate fully in the capital system without being filtered out by thin margins and engineered fragility. A county is sovereign when its residents can qualify at scale, own at scale, build at scale, and endure shocks without collapse. And that endurance is not abstract. It shows up as fewer foreclosures, fewer evictions, fewer abandoned properties, fewer desperate credit cycles, and a stronger, more predictable tax base that allows infrastructure to be built without squeezing families. It shows up as stabilized neighborhoods where families stay, schools stabilize, and communities invest. It shows up as a cultural shift where qualification becomes normal, savings becomes reinforced, credit discipline becomes common, and kids grow up watching adults around them move from survival to strategy. That is how generational transformation starts: not by promising the moon, but by engineering a system where the math finally works for the people who power this county.
So my promise to Miami-Dade is simple and non-negotiable: under a Residents-First Administration, we will build a county where the inputs are stronger, the approvals rise, the capital stays local, and the outcomes compound. Not because anyone gave us permission — but because we designed the structure to produce strength at scale. This county has talent. This county has work ethic. This county has builders, drivers, nurses, techs, teachers, entrepreneurs, and families who have carried Miami-Dade on their backs for years. The only thing missing has been an administration that understands that the gate to the future is underwriting math — and that the fastest way through that gate is not to complain about it, but to out-engineer it. That is what we are going to do. When residents qualify, billions flow. When billions flow locally, equity compounds. When equity compounds, Miami-Dade becomes resilient for generations.
Victor J. Rosario Residents-First Administration #UnleashingMiamiDadeCounty #TeamVictor
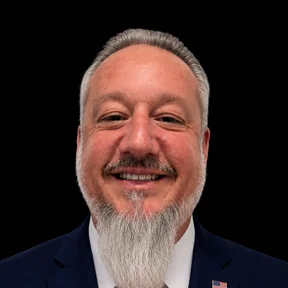
About Victor J. Rosario
Victor J. Rosario is the Residents-First candidate for Miami-Dade County Mayor 2028. A U.S. Coast Guard veteran, entrepreneur, technologist, and artist, Victor brings a track record of building real solutions — from AI tools to campaign policy — that serve Miami-Dade's 2.8 million residents.
Learn More About Victor